IME Case Studies
Real-world examples of how IME's twin-engine investment philosophy has delivered results
Eternal
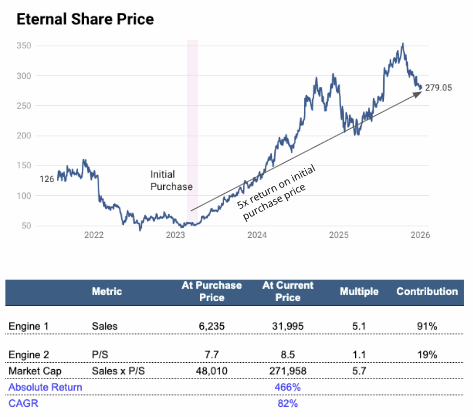
Rationale at Time of Investment
We bought Eternal after the stock had corrected by over 66% from its peak, on the back of a tremendous shift in market perception on tech companies (both in India & globally). We believed that this huge pessimism - investor’s were concerned on the very viability of loss-making digital platforms in India, was misplaced as investors were focusing on short-term losses, without appreciating how it laid the path to super-normal long-term profitability. This allowed us to buy into a very high growth (Engine 1) company, at a substantial discount (Engine 2) to its value.
Performance since Investment
Engine 1 (Sales per share): The business has seen tremendous growth, aided by the acquisition of Blinkit (BS cash converted to revenues), resulting in turnover increasing over 5 times in less than 3 years.
Engine 2 (P/Sales): While the bulk of the very strong performance of Eternal has been driven by a tremendous scaling up of the business (especially the acquired Quick-commerce of Blinkit), valuations have also moved up further boosting the share price movement.
Bharat Electronics
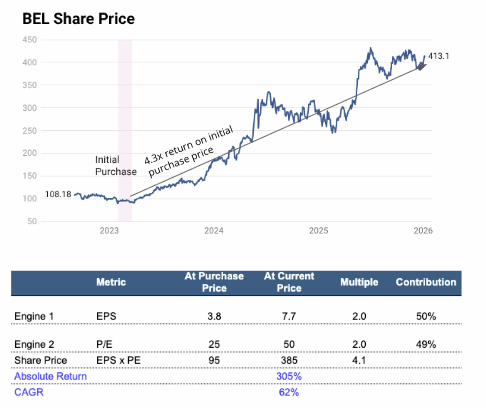
Rationale at Time of Investment
Defence has traditionally been a laggard sector in India - plagued by long lead-times, uncertain government orders and traditional focus on imports for key defence equipment. This lead to most defence companies trading at low valuations, with limited market interest.
We invested in BEL, at a time when the government's intention of Make-in-India and reduce dependence on imports was becoming clear. Given the very large proportion of Indian defence spends on imports, and growing geopolitical concerns that made this dependence a risk, we saw a very clear multi-year growth potential in BEL (Engine 1), combined with the potential for a re-rating (Engine 2) due to changing sector dynamics.
Performance since Investment
Engine 1 (EPS): Strong traction in order inflows & execution, on the back of the focus on reduced importance dependence, drove strong earnings growth.
Engine 2 (P/E): Improved sentiments on the longer-term growth potential of the sector, lead to a doubling of valuations - a powerful share price boost to the already strong earnings growth.
Shriram Transport Finance
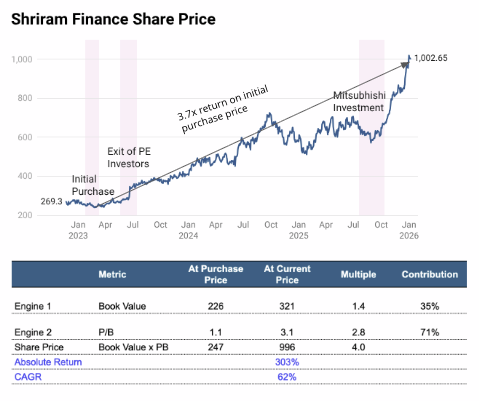
Rationale at Time of Investment
Shriram is the dominant leader in used CV financing—an attractive, high-yield niche with limited bank competition. However the combination of a weak industry cycle, combined with market fears of the technical overhang of Private Equity investor selling, lead to this highly attractive niche NBFC business being available at highly attractive valuations (Engine 2). Additionally, we were also confident of the long-term growth potential of the business and a shorter-term improvement in growth rates (Engine 1).
Performance since Investment
Engine 1 (BVPS): SF has delivered consistent growth since our investment, with a substantial improvement in growth prospects driven by the SCUF merger and the Mitsubishi investment.
Engine 2 (P/B): While the company has grown well, what has really driven the stock price movement is an improvement in multiples from 1x to 3x book. This was initially aided by the actual exit of PE investors (reducing the risk), which was then further boosted by a clear improvement in sentiment on the growth outlook (as explained above).